Social Engineering: Why Scams Work on Anyone
Social engineering is the part of a scam that happens in the conversation rather than in the technology. Instead of breaking into an account, someone persuades the account holder to open the door: to read out a code, install an app, approve a login, or send a payment. It works through authority, urgency, familiarity, and secrecy, and it works on careful people, which is the whole reason it is the method of choice.
Why it works on anyone
Most of what a person does in a day is automatic, and it has to be. When a situation resembles something familiar, like a notice from the bank or a request from a family member, nobody stops to examine every detail, and the scammer builds the story to fit that shape. The Cybersecurity and Infrastructure Security Agency describes the same mechanics on its page on recognizing and reporting phishing: a request that sounds urgent, a consequence for not acting, and a channel you did not choose.
The scale of it says something about how well it works. In the FBI Internet Crime Complaint Center’s 2025 Internet Crime Report, phishing and spoofing was the most frequently reported crime type, with 191,561 complaints, and those complaints come from every age group and every income level. Falling for one of these conversations is not a personal failing. The fault belongs to the person running it, every time.
The name sounds technical, but the situation is usually ordinary: a call that seems to come from the bank, a message from a relative on a new number, someone offering help with a computer problem, or a bill that has to be settled quickly.
How the trust gets built
The conversation often opens with something correct, a professional tone, or a small favor. The request comes later, once the frame is set. Authority, likeability, fear, urgency, and secrecy are all used to reduce the number of questions a person would normally ask.
Secrecy is the one people underestimate. A request not to tell anyone, framed as an active investigation or an embarrassment to avoid, exists to keep you from saying the story out loud to a second person, because saying it out loud is what usually ends it.
An example
Someone calls saying they are from your bank’s security team and mentions your full name and the town you live in. Then comes the request: install an app so the charge you did not make can be reversed. The correct detail is what opens the conversation, and access to the device is what the call was for.
Real details about you do not prove identity
A name, a phone number, an address, the last four digits of a card, the name of a recent purchase: all of it can come from marketing lists, public records, a social profile, or a data breach. Our guide to what to do after a data breach covers how much of this ends up in circulation.
The conversation itself hands over more. When someone asks do you recognize a 2,400 dollar charge, any answer helps them tune the story, and a correction from you fills in a blank they did not have. That is why a caller who knows things about you is not thereby verified.
So do not authenticate a stranger by what they know. Authenticate the channel instead: end the contact and reach the institution through a number or an app you already had. The FTC makes the same point across its guidance on impostor scams, where the recurring instruction is to contact the company yourself rather than through anything the contact provided.
The most common forms
Any interaction can carry it: in person, by phone, by email, or through a social account. In the scams that go after ordinary people’s money, a few forms come up again and again.
- An invented reason to make contact: a suspicious purchase, a problem with your records, a relative in trouble. It is the basis of the fake fraud department that calls you.
- Bait: a prize, a steep discount, an easy job, or money waiting for you, leading to a link or to a fee to release it. It shows up constantly in fake emails and messages.
- Offered help: someone presents themselves as tech support for a problem you did not know you had and asks you to install a program or read out a code. We cover the version built around a payment in refund scams.
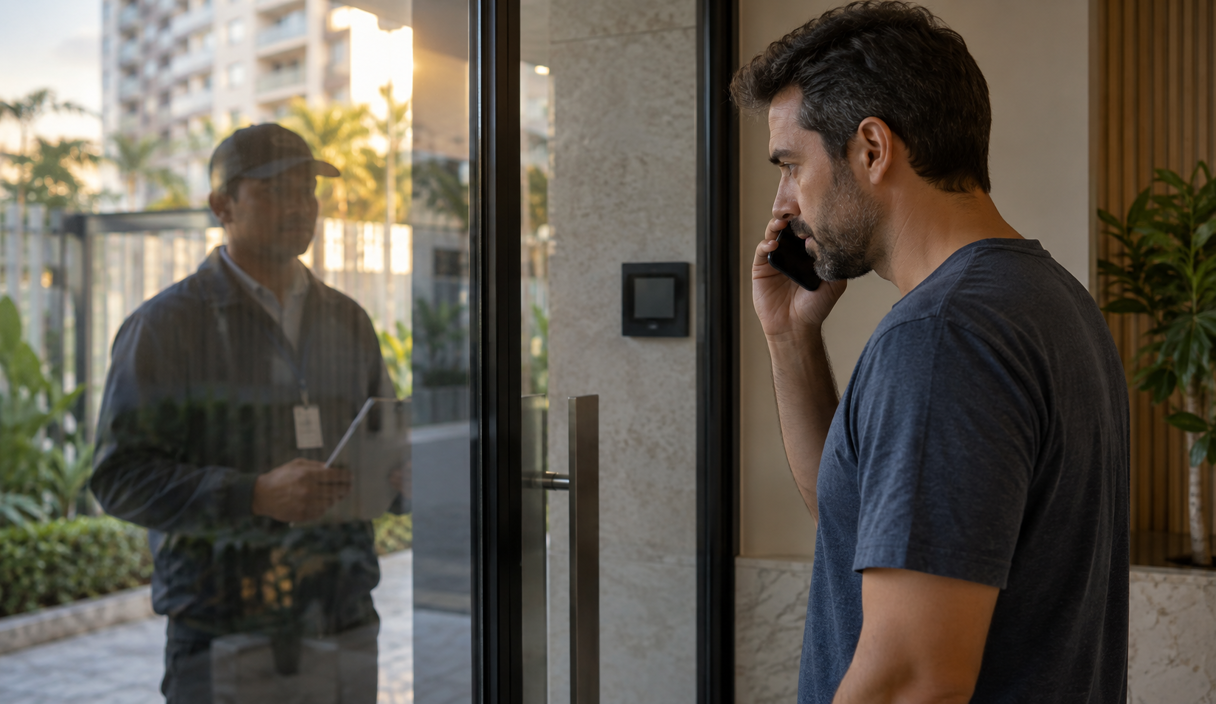
- In person: a courier sent to collect a card or cash from your door, or a collection for a charity drive that does not exist. The in-person version has been part of impostor scams for years and it has not gone away.
- A short text message: a package, a toll, expiring points, or an account about to be locked, which is what smishing means.
- A payment instruction that changes: an invoice you were expecting arrives with new bank details, or a seller asks you to switch to a different payment method at the last minute.
Situations where it shows up
- a caller who insists that the line must stay open while you do something;
- a relative on a new number asking for money, which is the shape of grandparent scams;
- support that arrives without having been called;
- an unexpected change to the account you were told to pay;
- a request for secrecy, which exists to stop you from asking a second person;
- a payment method that has to be a gift card, a wire, cryptocurrency, or an instant transfer to a person, all of which are hard to reverse. The FTC covers the first of those in gift card scams.
None of these turn every conversation into a fraud. What they do is mark the moment when it is worth leaving the script you were handed and checking the situation some other way.
How to break the pressure
End the contact and pick the next step yourself. Call the relative on the number you already had, open the bank app you installed, or find the company’s number on a statement or a card. You do not have to argue, explain, or prove to the person that you noticed something was off.
A pause is the cheapest defense there is. Almost nothing that is real gets worse because you waited ten minutes and called someone back, and almost everything that is fake does.
It also helps to agree on a few things with your family before any of this happens: a word that gets asked for when money is requested in a hurry, an agreement that nobody sends a payment on the strength of a message alone, and a habit of calling the old number to check. For an older relative who is a frequent target, our guide to elder financial abuse covers the warning signs a family notices first and who to call.
If you already gave information or money
- Call your bank right away, through the app or the number on the back of your card, and tell them what happened. Ask what recovery options exist on the payment type you used, because a card charge, a wire, and an instant payment to a person are not in the same position. The CFPB explains the general rules for an unauthorized transaction.
- If you gave a password or a code, change the password in the official app or site and turn on two-factor authentication, which asks for a second code on top of the password. If the code was for a messaging account, follow the steps in what to do when a messaging account is stolen.
- If you installed something during the conversation, disconnect that device from the internet, use another one for your bank and your passwords, and sign out any connected device you do not recognize.
- Tell your family and your contacts through another channel, so that nobody answers a request for money made in your name, and so they know the account may be in someone else’s hands.
- File the reports. A police report first, because banks and creditors ask for one, then the FTC at ReportFraud.ftc.gov and the FBI’s Internet Crime Complaint Center. If personal information was exposed, IdentityTheft.gov builds a recovery plan step by step.
One last thing worth saying plainly, because people carry it for a long time afterward: these conversations are built by people who run them for a living, refine them constantly, and reach thousands of others with the same script. Being on the receiving end of a good one says nothing about your judgment.
Social engineering FAQ
What is the difference between social engineering and phishing?
Social engineering is the broader idea: persuading a person to act against their own interest. Phishing is one delivery method for it, usually a fake message or page. A phone call, a text, a message from a hacked friend’s account, and someone at your front door are all social engineering too. The defense is the same across all of them, which is why the broader name is useful.
Does it only work on people who are not paying attention?
No. These scripts are written to work on people who are busy and competent, and they are tested on thousands of people until the wording is right. They use a real name, a correct detail, a plausible problem, and a deadline. Attention is not what decides it, and treating it as though it were is exactly what keeps people from reporting.
How do I check that a caller is really from my bank?
End the call and dial the number on the back of your card or the one in the bank’s app, then ask whether anyone there was trying to reach you. Do not call back from your recent calls list, and do not judge it by the number that appeared on screen, since that can be falsified. The same approach works for a government agency: find the number on its own site rather than in the message.
Why do scammers ask you not to tell anyone?
Because a second person almost always breaks the spell. The request usually comes dressed as an investigation that must stay confidential, or as something embarrassing you would not want shared. Treat a request for secrecy as a reason to tell someone immediately, and pick the person yourself rather than the one the caller suggests.
How can I help a relative who keeps getting these calls?
Agree in advance on what happens when money comes up: a word the family asks for, a rule that nobody pays on the strength of a call or a message alone, and a habit of calling back on a number already in the phone. Make it easy to bring you a suspicious call without embarrassment, because shame is what keeps people quiet long enough for the money to move.
Keep reading
Impostor Scams: Government, Business, and Family Impersonation Explained
One mechanism behind many scams: someone you trust, a problem invented, and a payment that cannot be undone.
7 min readRead
Grandparent Scams: How the Emergency Story Works and How Families Can Prepare
The urgent call about a grandchild, why a cloned voice changes nothing about the defense, and the family password.
6 min readRead
Gift Card Scams: How They Work and What to Do If You Paid
Why no real agency or company asks for gift cards, and the call to make in the first minutes after paying.
5 min readRead